Filer, recipient and account boxes
One box for the filer's name, address and telephone number, then the filer's TIN, the recipient's TIN, name and address, the account number, the CUSIP number and the applicable checkbox on Form 8949.
1099-DA
Digital Asset Proceeds from Broker Transactions
This is the 2025 edition of Form 1099-DA, Digital Asset Proceeds From Broker Transactions, an older edition kept for tax year 2025. The year box on the form reads 2025. The IRS About page says the form is used to report digital asset proceeds from broker transactions. It also lists two developments for this year: Form 1099-DA was excluded from the Combined Federal/State Filing Program for tax year 2025, and corrections to the 2025 Instructions for Form 1099-DA on de minimis rules and optional reporting methods were posted 07-JAN-2026.
A broker completes the form. The broker files Copy A with the IRS, gives Copy B to the customer, called the recipient, uses Copy 1 for a state tax department and gives Copy 2 to the recipient for a state income tax return when required. The recipient instructions on the form say brokers must report proceeds from (and in some cases, basis for) digital asset dispositions to the recipient and the IRS on Form 1099-DA.
The form says Copy A printed from this PDF is for information only because it is not scannable, while Copy B and the other copies in black may be printed and given to the recipient. You can fill out this edition free in your browser on this page and download it without an account.
One box for the filer's name, address and telephone number, then the filer's TIN, the recipient's TIN, name and address, the account number, the CUSIP number and the applicable checkbox on Form 8949.
The code for the digital asset, the name of the digital asset and the number of units sold, exchanged, or otherwise disposed of.
Date acquired, date sold or disposed, proceeds, cost or other basis, accrued market discount and wash sales loss disallowed.
Basis reported to IRS, gross or net proceeds, QOF, federal income tax withheld, loss not allowed, short-term, long-term or ordinary gain or loss, cash only, customer-provided acquisition information and noncovered security.
Aggregate reporting for qualifying stablecoins or specified NFTs, the number of transactions, first sales by a creator or minter, units transferred in and the transfer-in date. Boxes 10 and 13 are reserved.
State name, state identification number and state tax withheld, with two lines for two states.
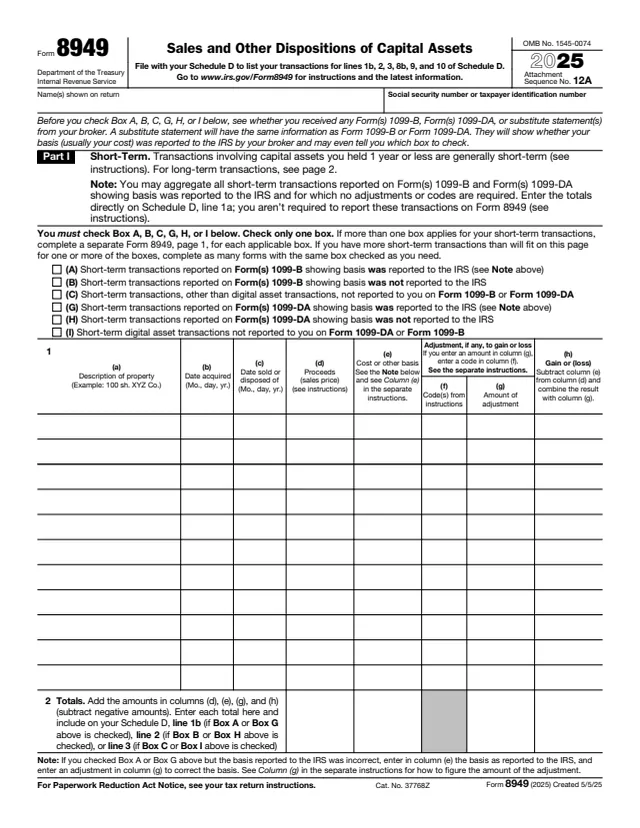
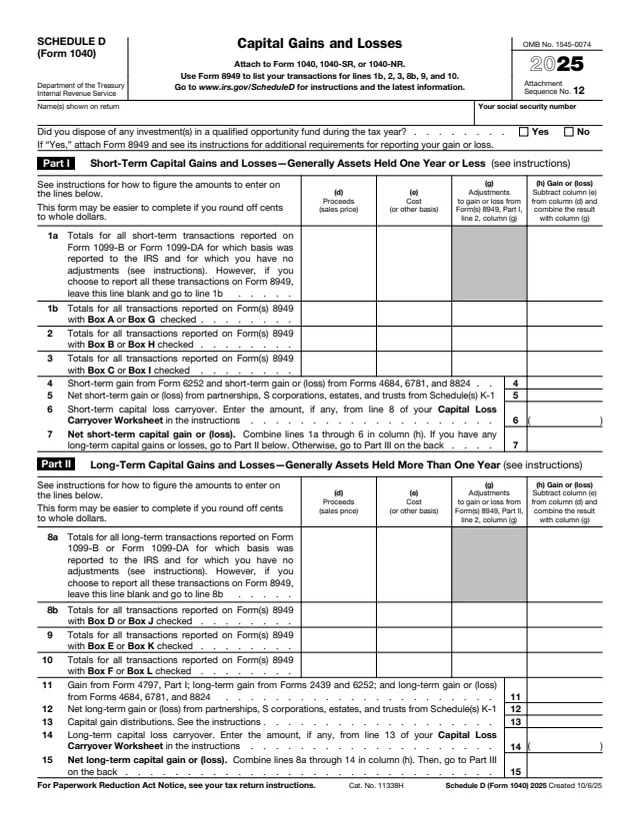
The form says this box shows where to report the transaction on Form 8949 and Schedule D (Form 1040), and which checkbox applies.
Box 1a holds the Digital Token Identification Foundation (DTIF) code for the asset named in box 1b. Box 1c holds the number of units sold, exchanged, or otherwise disposed of.
Box 1d is the original acquisition date. The form says it may be blank if box 9 is checked, the assets were acquired on a variety of dates or the date was unknown to the filer. Box 1e is the sale or disposition date.
Box 1f is total proceeds, which may include cash and the value of services, digital assets or other property received. If box 9 is checked, box 1g may be blank when basis was unknown to the filer or the assets were acquired prior to 2026.
Box 2 is checked when the basis in box 1g has been reported to the IRS, and then the short-term or long-term box in box 6 is checked. Box 9 marks a noncovered security, and boxes 1d, 1g, 1h, 1i, 2 and 6 may then be blank.
Box 4 shows backup withholding. Box 11a is checked when box 1f is an aggregate amount for qualifying stablecoins or specified NFTs, with the number of transactions in box 11b. Boxes 12a and 12b show units transferred in and the transfer-in date.
These steps follow the box descriptions printed on the 2025 form. The IRS About page links the current instructions.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Copy A goes to the Internal Revenue Service Center, Copy B to the recipient, Copy 1 to a state tax department and Copy 2 to the recipient for a state income tax return when required.
The form says not to print and file Copy A downloaded from the IRS website, because a penalty may be imposed for filing information returns that can't be scanned.
The form says a filer with 10 or more information returns may be required to e-file, and points to IRS.gov/InfoReturn. Official scannable forms can be ordered at IRS.gov/EmployerForms.
The IRS About page says Form 1099-DA was excluded from the Combined Federal/State Filing Program for tax year 2025.
The About page lists corrections to the 2025 Instructions for Form 1099-DA covering de minimis rules for reporting certain sales of digital assets and optional reporting methods, posted 07-JAN-2026.
The form says Copy B may show only the last four digits of the recipient's TIN, but the issuer has reported the complete TIN to the IRS.
8949
202 fields, 2 pages
1040
55 fields, 2 pages

1040
199 fields, 2 pages
W-9
23 fields, 6 pages
1099-B
163 fields, 7 pages
Brokers complete and file the form. The customer receives Copy B, which the form marks "Keep for your records."
No tool matches that search.
The year box on this PDF reads 2025, so it is the 2025 edition of Form 1099-DA. The IRS About Form 1099-DA page links the current revision.
A broker. The recipient instructions on the form say brokers report proceeds from, and in some cases basis for, digital asset dispositions to the customer and the IRS on Form 1099-DA.
The form says box 1g may be blank if box 9 is checked and the basis was unknown to the filer or the assets were acquired prior to 2026. It says that when box 1g is blank, basis comes from the recipient's own books and records.
It shows gross proceeds from the first sale of any specified NFTs the recipient created or minted. The form says those proceeds are not included in box 1f.
The form says it may show only the last four digits of the TIN for the recipient's protection. The issuer has reported the complete TIN to the IRS.
No. The IRS About page says Form 1099-DA was excluded from the Combined Federal/State Filing Program for tax year 2025.