Line 1: carryforward from 2024
The amount from line 4 of the 2024 Form 8859.
8859
Carryforward of the District of Columbia First-Time Homebuyer Credit
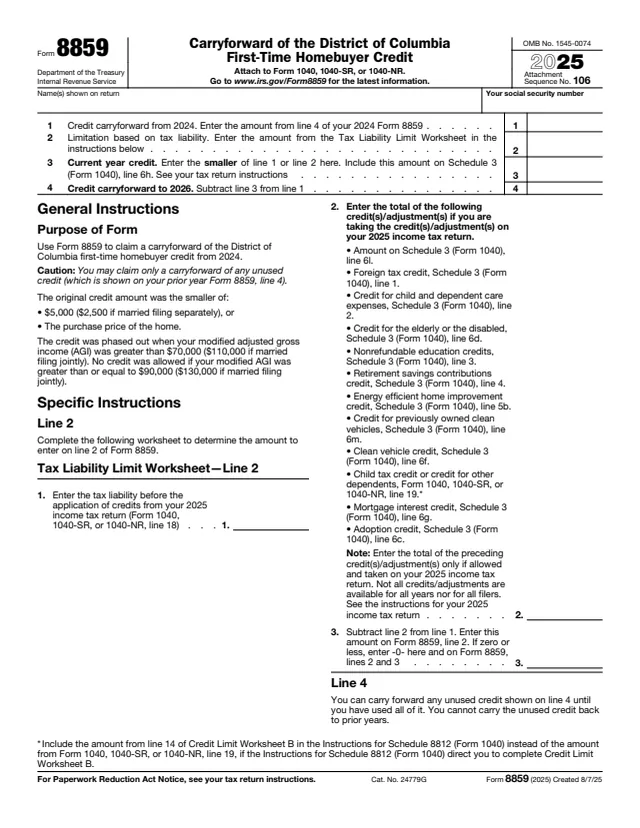
Form 8859, Carryforward of the District of Columbia First-Time Homebuyer Credit, is used to claim a carryforward of that credit from 2024. It is attached to Form 1040, 1040-SR or 1040-NR. The 2025 form has four lines: the carryforward from line 4 of the 2024 Form 8859, a limit based on tax liability, the current year credit, and the carryforward to 2026.
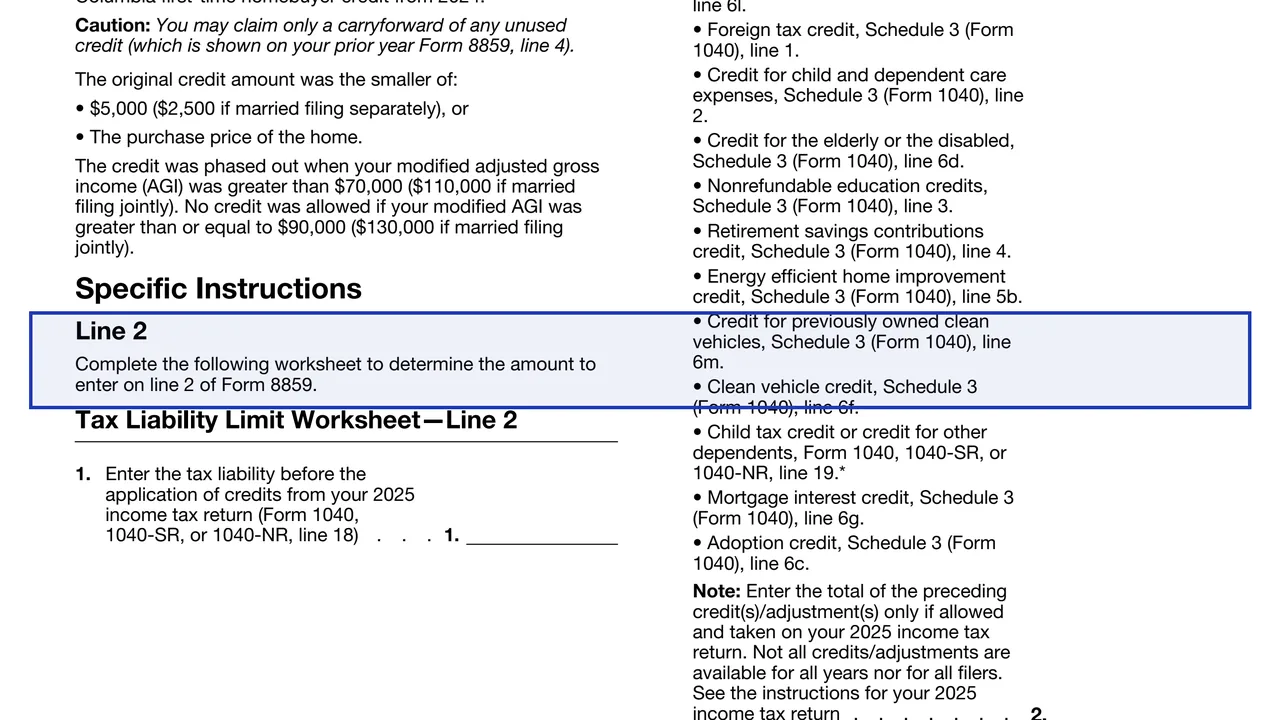
The form says only a carryforward of any unused credit, shown on the prior year Form 8859, line 4, may be claimed. As background, it says the original credit amount was the smaller of $5,000 ($2,500 if married filing separately) or the purchase price of the home. Its instructions, including the Tax Liability Limit Worksheet for line 2, are printed on the form itself.
You can fill out the PDF free in your browser on this page and download it without an account.
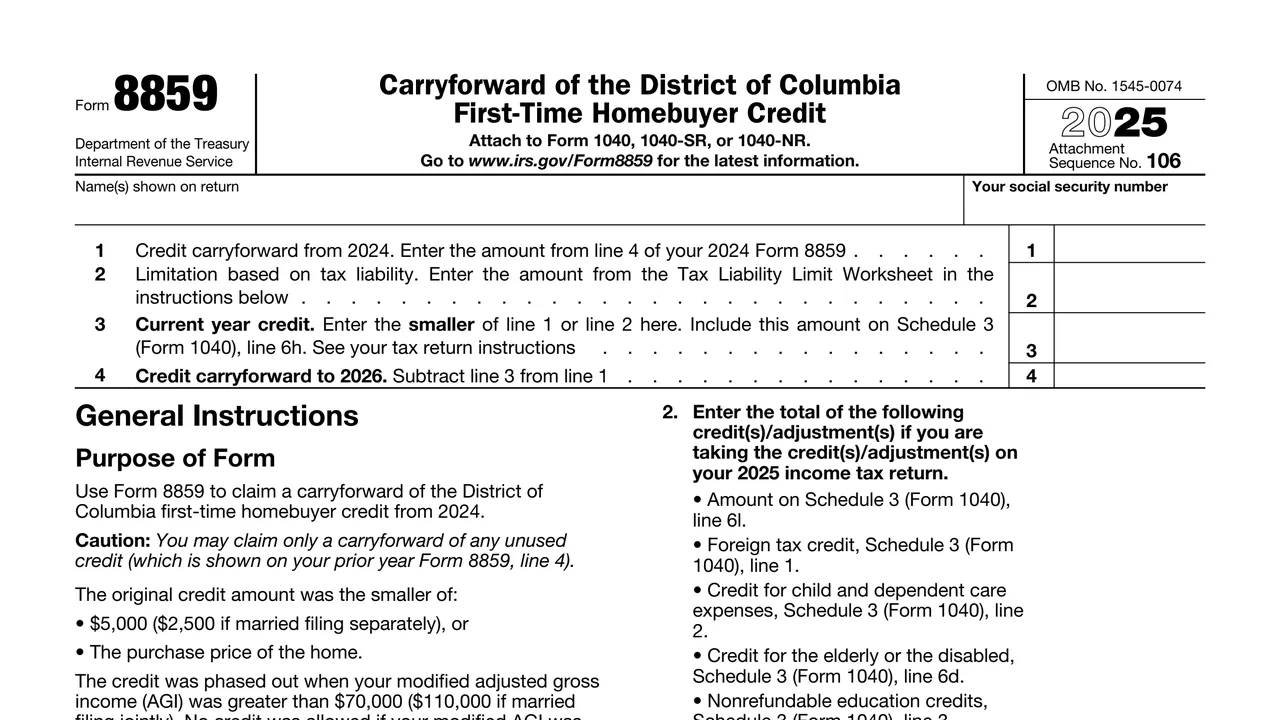
The amount from line 4 of the 2024 Form 8859.
The amount from the Tax Liability Limit Worksheet in the instructions on the form.
The smaller of line 1 or line 2, which is included on Schedule 3 (Form 1040), line 6h.
Line 1 minus line 3.
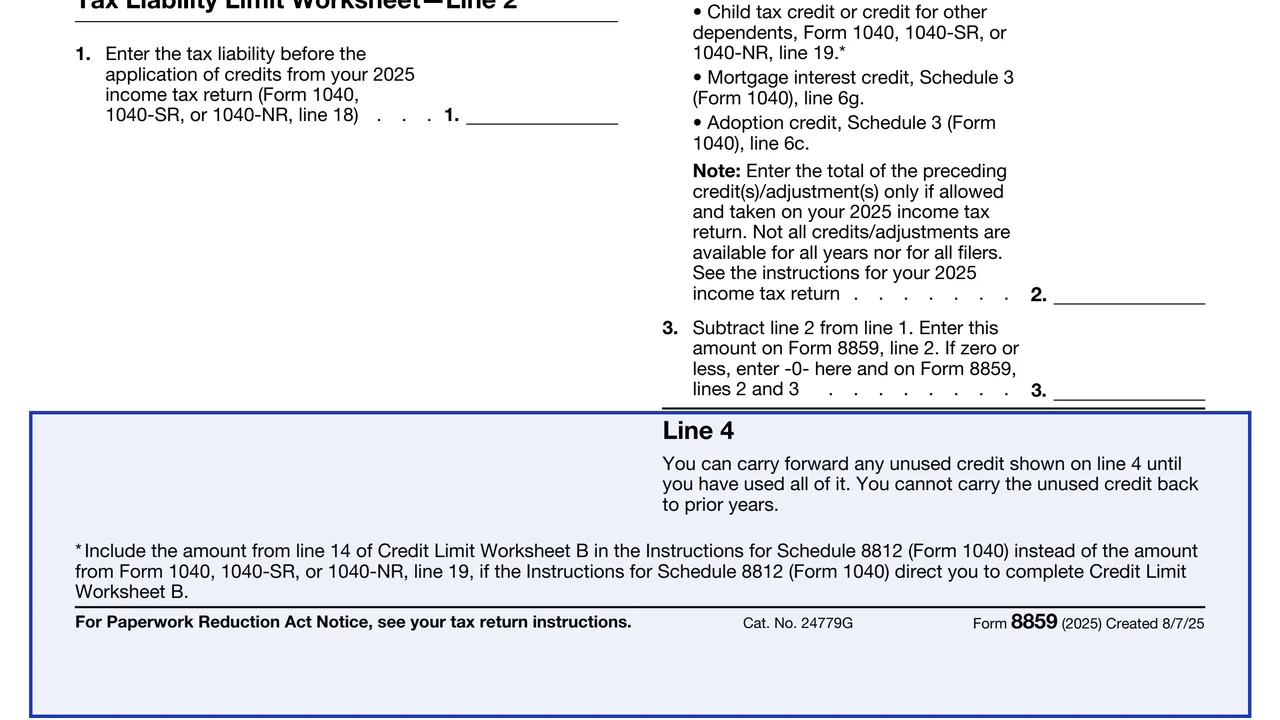
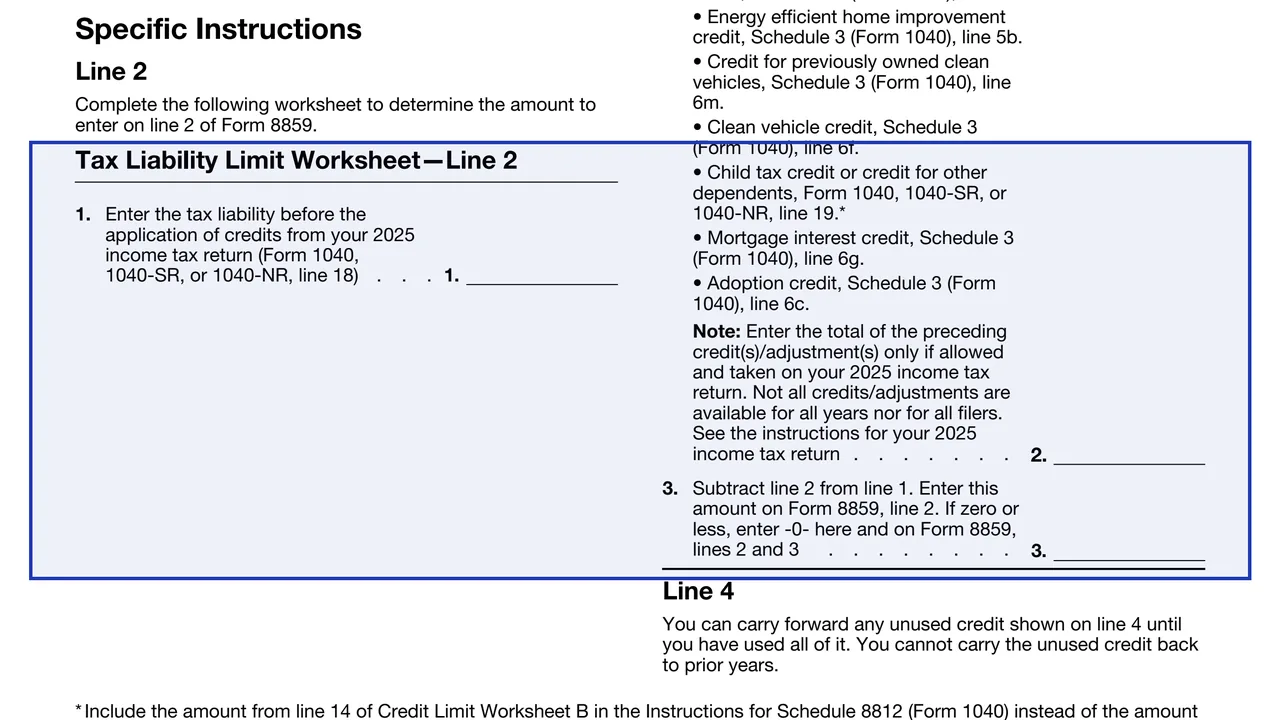
Three lines: the tax liability before credits from the 2025 return, the total of the listed credits and adjustments taken, and the difference.
Enter the amount from line 4 of the 2024 Form 8859.
Enter the tax liability before the application of credits from the 2025 return: line 18 of Form 1040, 1040-SR or 1040-NR.
Total the listed credits taken on the 2025 return, such as the foreign tax credit, the child and dependent care credit, education credits and the child tax credit. The form says to include them only if allowed and taken.
Subtract worksheet line 2 from line 1 and enter the result on Form 8859, line 2. If zero or less, enter -0- there and on lines 2 and 3 of the form.
Enter the smaller of line 1 or line 2. Include this amount on Schedule 3 (Form 1040), line 6h.
Subtract line 3 from line 1. The form says the unused credit can be carried forward until all of it is used, and cannot be carried back.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1040, 1040-SR or 1040-NR. Its attachment sequence number is 106.
The line 3 amount is included on Schedule 3 (Form 1040), line 6h.
Any unused credit on line 4 carries forward until it is used. The form says it cannot be carried back to prior years.
If the Instructions for Schedule 8812 (Form 1040) direct completing Credit Limit Worksheet B, the form says to use line 14 of that worksheet instead of line 19 of the return.

1040
199 fields, 2 pages
1040-SR
200 fields, 4 pages
1040-NR
171 fields, 2 pages
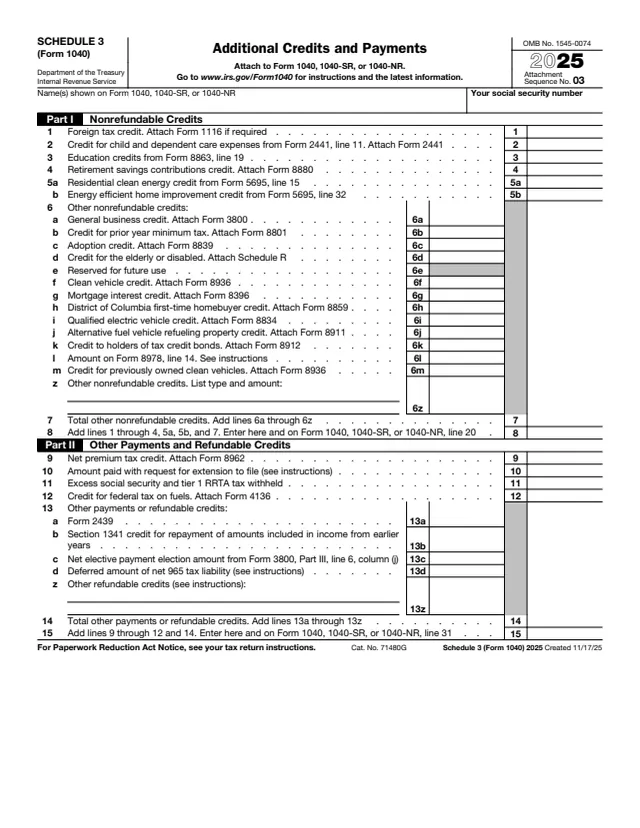
1040
37 fields, 1 page
1040
41 fields, 2 pages
The form is completed by individuals and attached to their own income tax return.
No tool matches that search.
The form says only a carryforward of any unused credit, shown on the prior year Form 8859, line 4, may be claimed.
On Schedule 3 (Form 1040), line 6h.
No. The form says it can be carried forward until all of it is used and cannot be carried back to prior years.
The form says the smaller of $5,000 ($2,500 if married filing separately) or the purchase price of the home.
The form says to enter -0- on worksheet line 3 and on Form 8859, lines 2 and 3.
The instructions are printed on the form itself, including the Tax Liability Limit Worksheet for line 2.