Lines 1, 2a and 2b: payer
The payer's name and the address where any IRS questions about Form 6497 can be directed.
6497
Information Return of Nontaxable Energy Grants or Subsidized Energy Financing
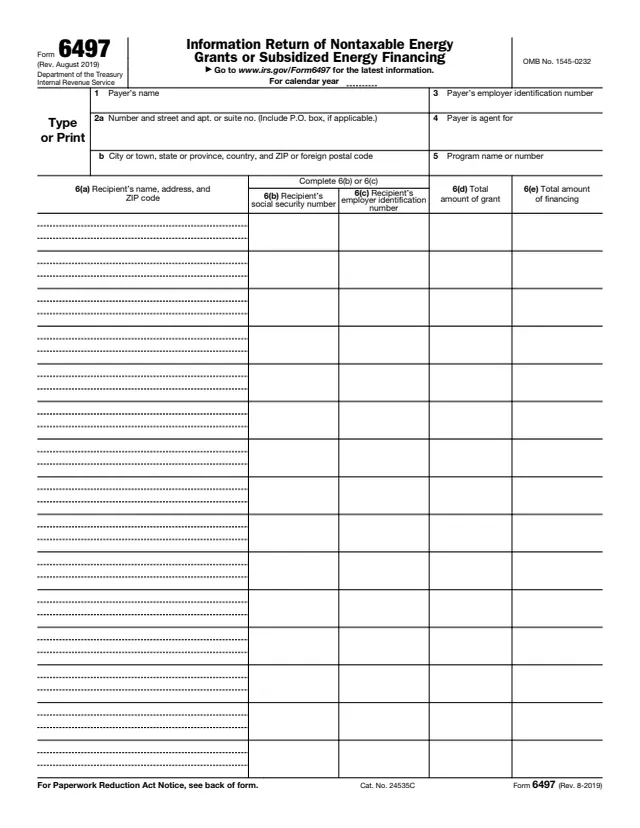
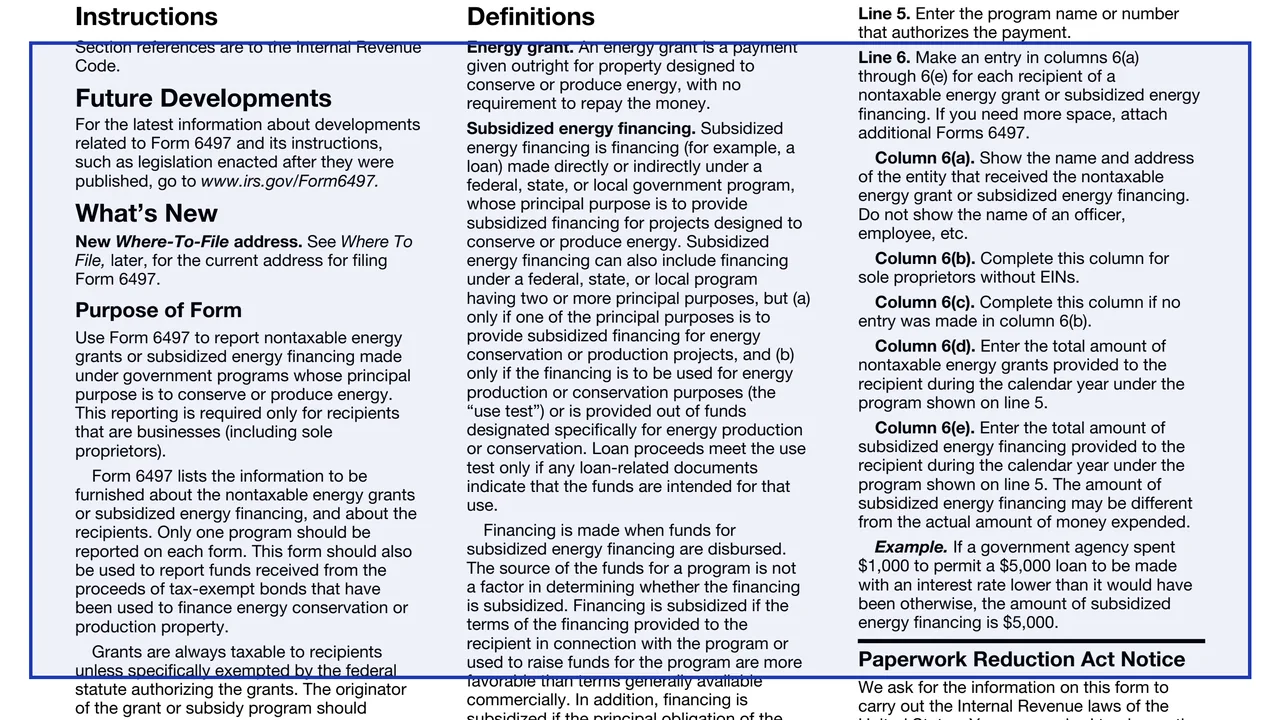
Form 6497 is an information return. Persons who administer government programs use it to report nontaxable energy grants or subsidized energy financing made under government programs whose principal purpose is to conserve or produce energy. The form says this reporting is required only for recipients that are businesses, including sole proprietors.
The form is filed by the payer, not by the business that received the money. Only one program is reported on each form, and the form is also used to report funds received from the proceeds of tax-exempt bonds used to finance energy conservation or production property. Taxable grants are reported on Form 1099-G instead.
The instructions are printed on page 2 of the PDF. You can fill out the form free in your browser on this page and download the result without an account.
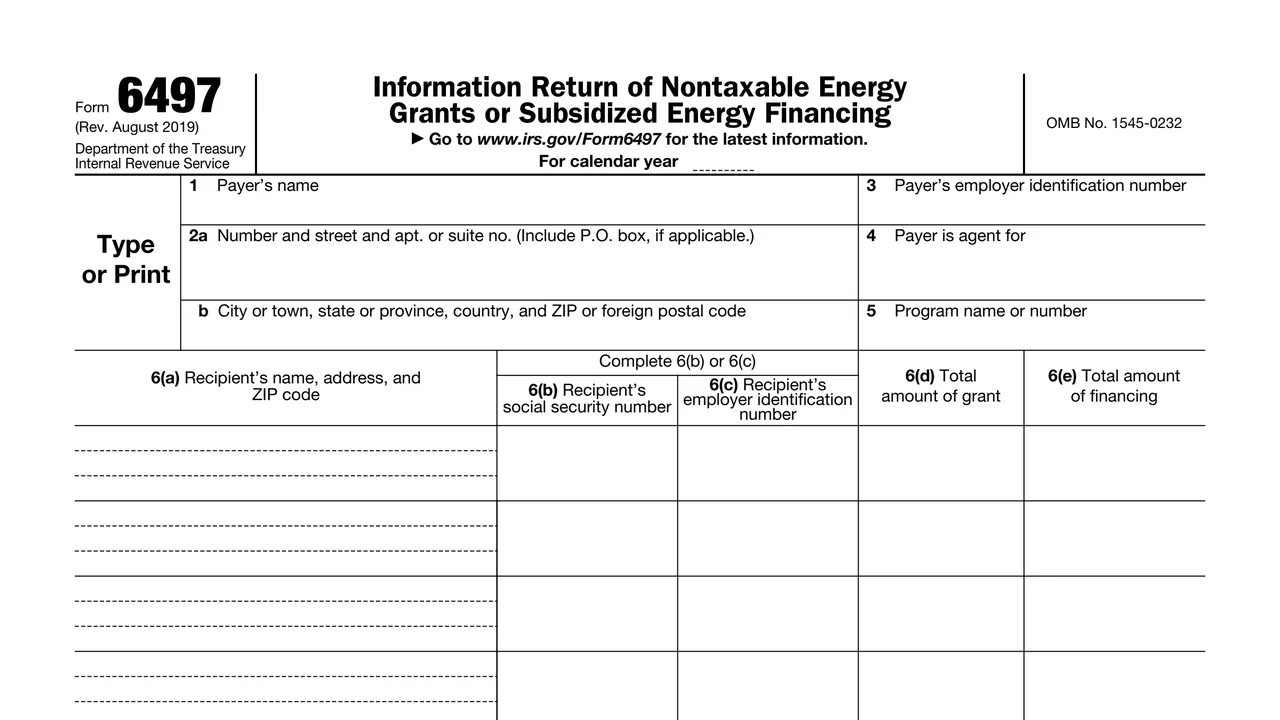
The payer's name and the address where any IRS questions about Form 6497 can be directed.
The payer's employer identification number, and the governmental entity for which an agent is administering the program.
The program name or number that authorizes the payment.
For each recipient: name and address in 6(a), social security number in 6(b) or employer identification number in 6(c), the total grant in 6(d) and the total financing in 6(e).
Purpose of the form, who files, when and where to file, definitions of energy grant, subsidized energy financing, payer and recipient, and line instructions.
Enter the name of the governmental entity that makes the grants or provides the financing. If an entity such as a bank administers the program as its designated agent, enter the agent's name and fill in line 4.
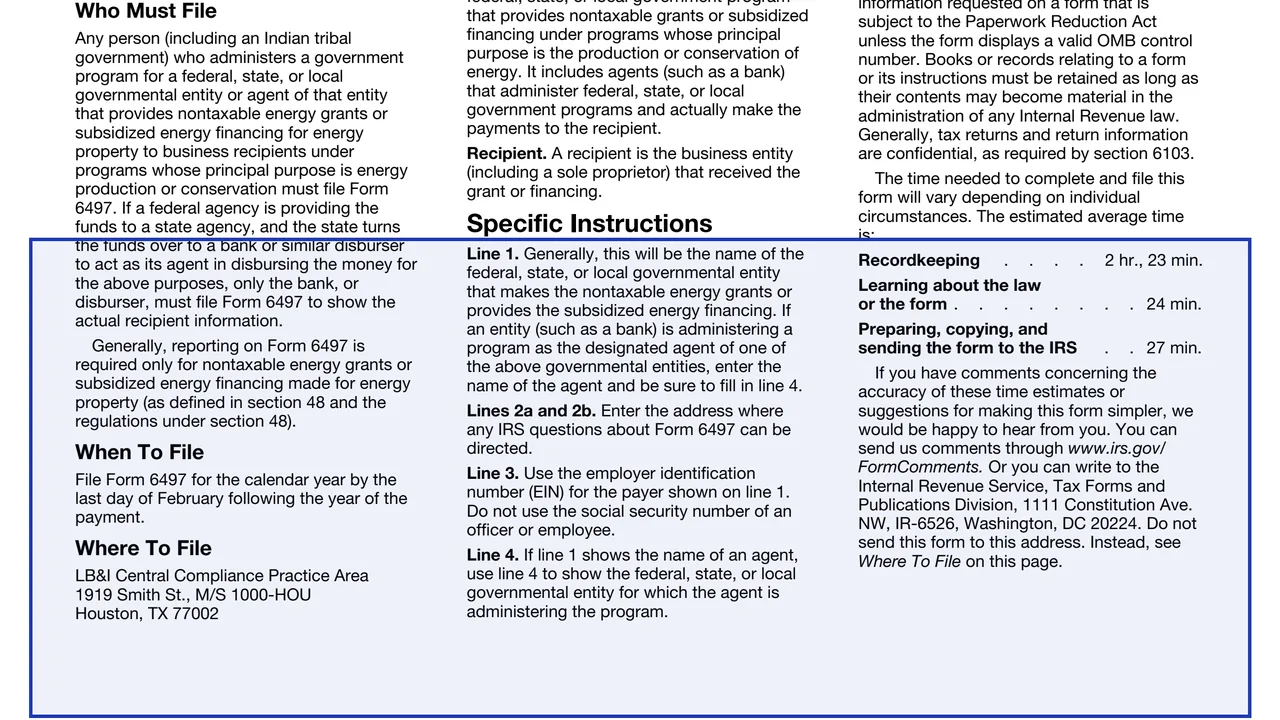
Enter the address for IRS questions, the payer's EIN (not the social security number of an officer or employee), the governmental entity on line 4 when line 1 is an agent, and the program name or number.
Show the name and address of the entity that received the grant or financing, not the name of an officer or employee. Complete 6(b) for sole proprietors without EINs, and 6(c) if no entry was made in 6(b).
Enter the total nontaxable energy grants and the total subsidized energy financing given to the recipient during the calendar year under the program on line 5. In the form's example, $1,000 spent to permit a $5,000 lower rate loan is $5,000 of subsidized energy financing.
Make an entry in columns 6(a) to 6(e) for each recipient. If more space is needed, the instructions say to attach additional Forms 6497.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Form 6497 for the calendar year by the last day of February following the year of the payment.
LB&I Central Compliance Practice Area, 1919 Smith St., M/S 1000-HOU, Houston, TX 77002. The What's New section says this is a new Where-To-File address.
The instructions say only one program should be reported on each form.
The Washington, DC address in the Paperwork Reduction Act Notice is for comments on the form. The form says not to send Form 6497 to that address.
The payer that administers the program completes and files the form. Recipients are listed on it but do not file it.
No tool matches that search.
The payer: a person, including an Indian tribal government, who administers a federal, state or local government program that gives nontaxable energy grants or subsidized energy financing to business recipients, or an agent such as a bank that actually makes the payments.
No. The recipient is listed on line 6 of the payer's form. The form is filed by the payer.
The instructions describe it as financing, for example a loan, made directly or indirectly under a federal, state or local government program whose principal purpose is to provide subsidized financing for projects designed to conserve or produce energy.
The instructions say by the last day of February following the year of the payment.
The form says taxable grants are reported on Form 1099-G, Certain Government Payments, and points to the Instructions for Form 1099-G.