Corporation and employee boxes
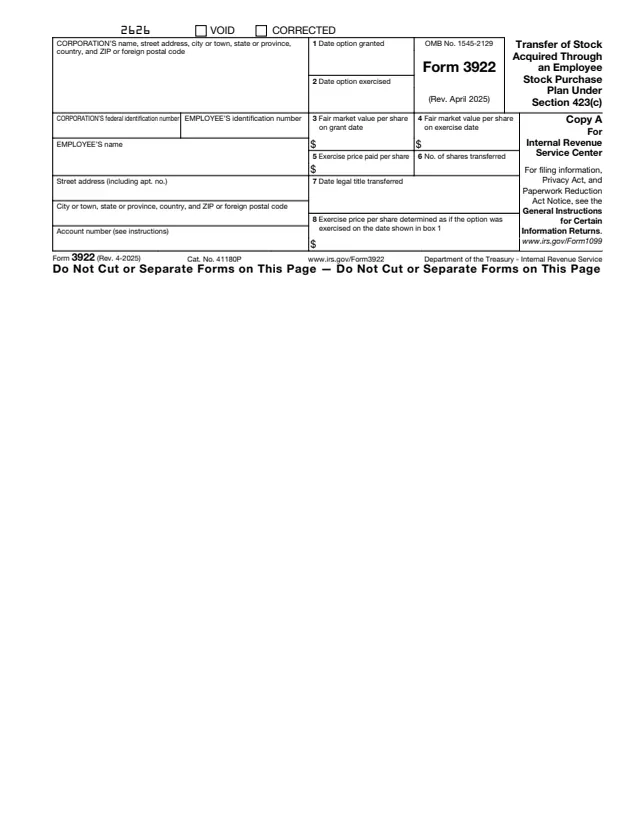
The corporation's name, address and federal identification number, the employee's identification number, name and address, and an account number.
3922
Transfer of Stock Acquired Through An Employee Stock Purchase Plan Under Section 423(c)
Form 3922 reports the transfer of stock acquired through an employee stock purchase plan under section 423(c). The instructions say every corporation that records, or has by its agent recorded, a transfer of legal title of a share acquired by exercising such an option files Form 3922 for each transfer made during the calendar year, where the exercise price is less than 100% of the value of the stock on the date of grant, or is not fixed or determinable on that date.
Copy A is for the Internal Revenue Service Center and Copy B is for the employee. The Instructions for Employee on Copy B say no income is recognized when an option under an employee stock purchase plan is exercised, that gain or loss is recognized (reported) for the year the stock is sold or otherwise disposed of, and to keep the form to figure it.
You can fill out Form 3922 free in your browser on this page and download the result without an account.
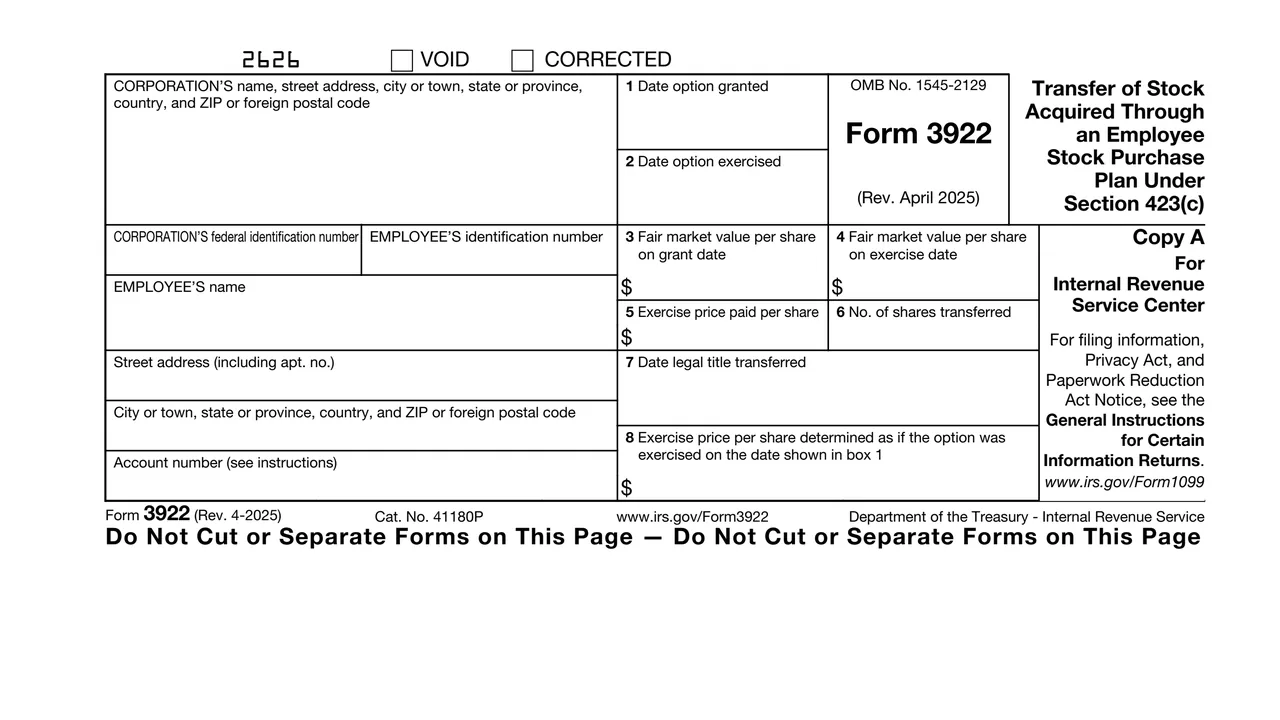
The corporation's name, address and federal identification number, the employee's identification number, name and address, and an account number.
The date the option was granted and the date the option was exercised.
Fair market value per share on the grant date and on the exercise date, and the exercise price paid per share.
The number of shares transferred and the date legal title was transferred.
The exercise price per share determined as if the option was exercised on the date shown in box 1, filled in only when that price was not fixed or determinable on that date.
VOID and CORRECTED boxes at the top, Copy A for the Internal Revenue Service Center, and Copy B for the employee with the Instructions for Employee.
Enter the name, address and TIN of the transferor. The instructions allow truncating the recipient's TIN on payee statements, but not on documents filed with the IRS, and the payer's TIN may not be truncated on any form.
The instructions say an account number is required when there are multiple accounts for one transferor with more than one Form 3922, and the IRS encourages one on every Form 3922.
Enter the grant date, the exercise date, the fair market value per share on each of those dates, and the price paid per share on the exercise date.
Enter the number of shares to which legal title was transferred and the date legal title of the shares was first transferred.
If the exercise price per share was not fixed or determinable on the grant date in box 1, enter it as if the option was exercised on that date. If it was fixed or determinable, the instructions say to leave box 8 blank.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Copy A goes to the Internal Revenue Service Center and Copy B to the employee. For filing information, the form points to the General Instructions for Certain Information Returns.
The Form 3922 instructions print no due dates. They say the General Instructions for Certain Information Returns cover when and where to file.
The instructions say the e-file threshold was lowered to 10, counted by aggregating all information returns, for returns required to be filed on or after January 1, 2024. IRIS is the IRS online portal for e-filing information returns.
The instructions say Copies A and B of Form 3922 have been made fillable online in a pdf format at IRS.gov/Form3922.
The instructions say to use them for tax year 2025 and later years until a superseding revision is issued.
The instructions say the corporation whose stock is being transferred files Form 3922 and furnishes a statement to the transferor, the employee who acquired the shares.
No tool matches that search.
The instructions say the corporation whose stock is being transferred files Form 3922 for each first transfer of legal title of stock acquired under a section 423(c) employee stock purchase plan.
Copy B is marked keep for your records. The Instructions for Employee say to keep the form and use it to figure gain or loss when the stock is sold or otherwise disposed of.
The Instructions for Employee say no income is recognized when an option under an employee stock purchase plan is exercised.
The instructions say to leave box 8 blank when the exercise price per share is fixed or determinable on the grant date in box 1.
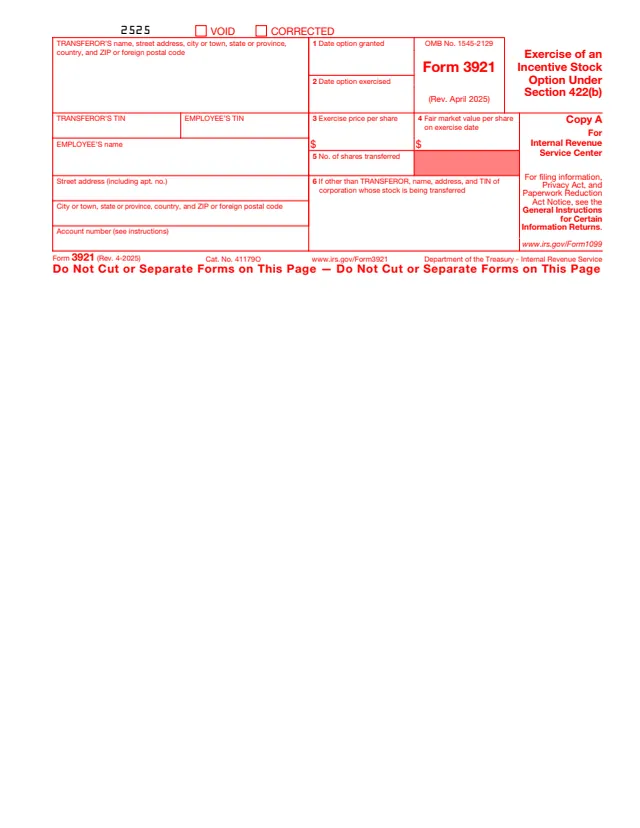
One set of instructions covers both. Form 3921 reports the exercise of an incentive stock option under section 422(b), and Form 3922 reports a transfer of stock acquired through an employee stock purchase plan under section 423(c).