Tax year
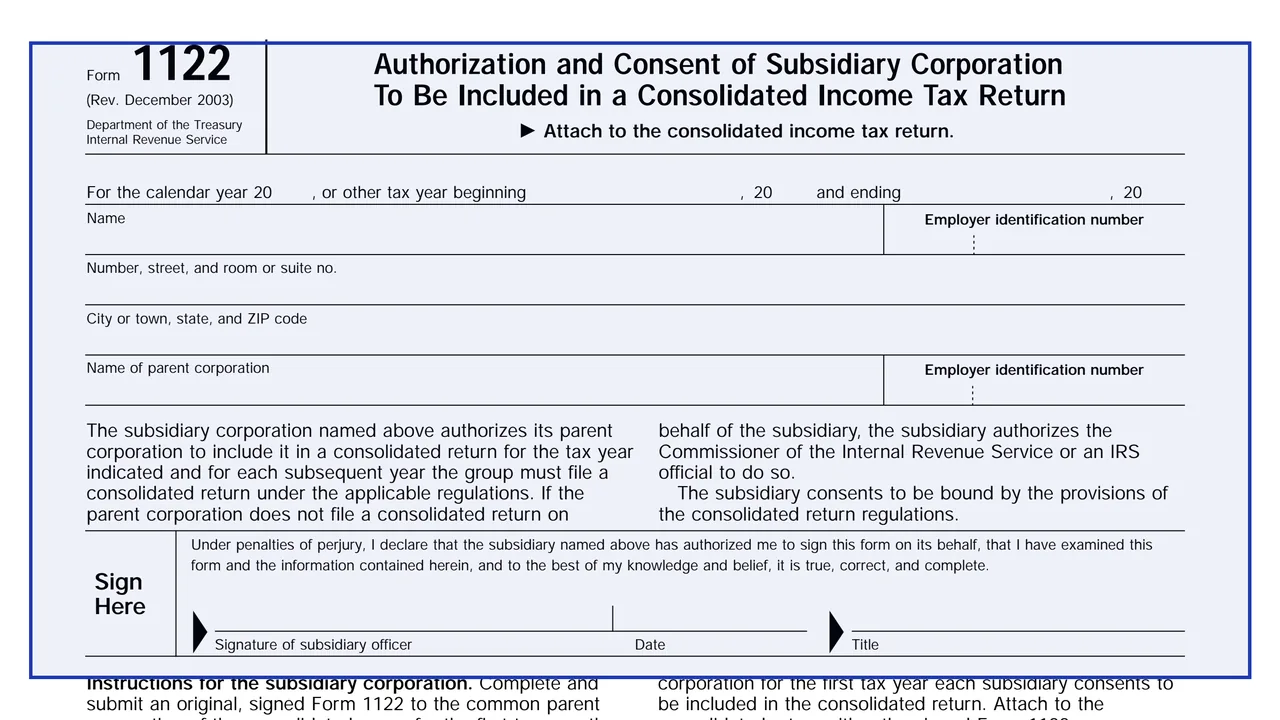
Spaces for the calendar year, or for another tax year with its beginning and ending dates.
1122
Authorization and Consent of Subsidiary Corporation to be Included in a Consolidated Income Tax Return
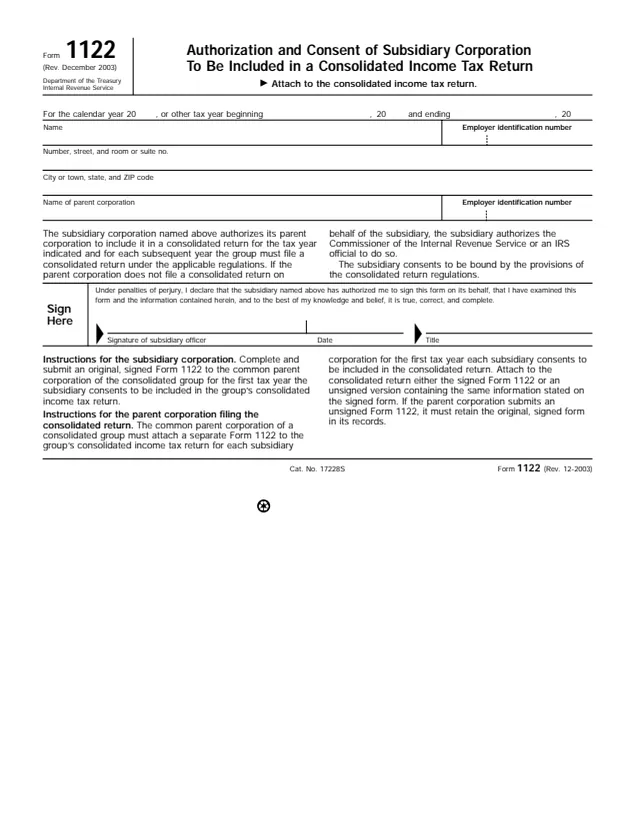
Form 1122, Authorization and Consent of Subsidiary Corporation To Be Included in a Consolidated Income Tax Return, is a one-page form a subsidiary corporation signs to join its group's consolidated return. The IRS About page says subsidiary corporations submit it to the common parent corporation of the consolidated group for the first tax year the subsidiary consents to be included.
By signing, the subsidiary authorizes its parent to include it in a consolidated return for the tax year shown and for each later year the group files one under the regulations, and it consents to be bound by the consolidated return regulations. The parent then attaches the form to the consolidated income tax return.
You can fill it out free in your browser on this page and download the result without an account.
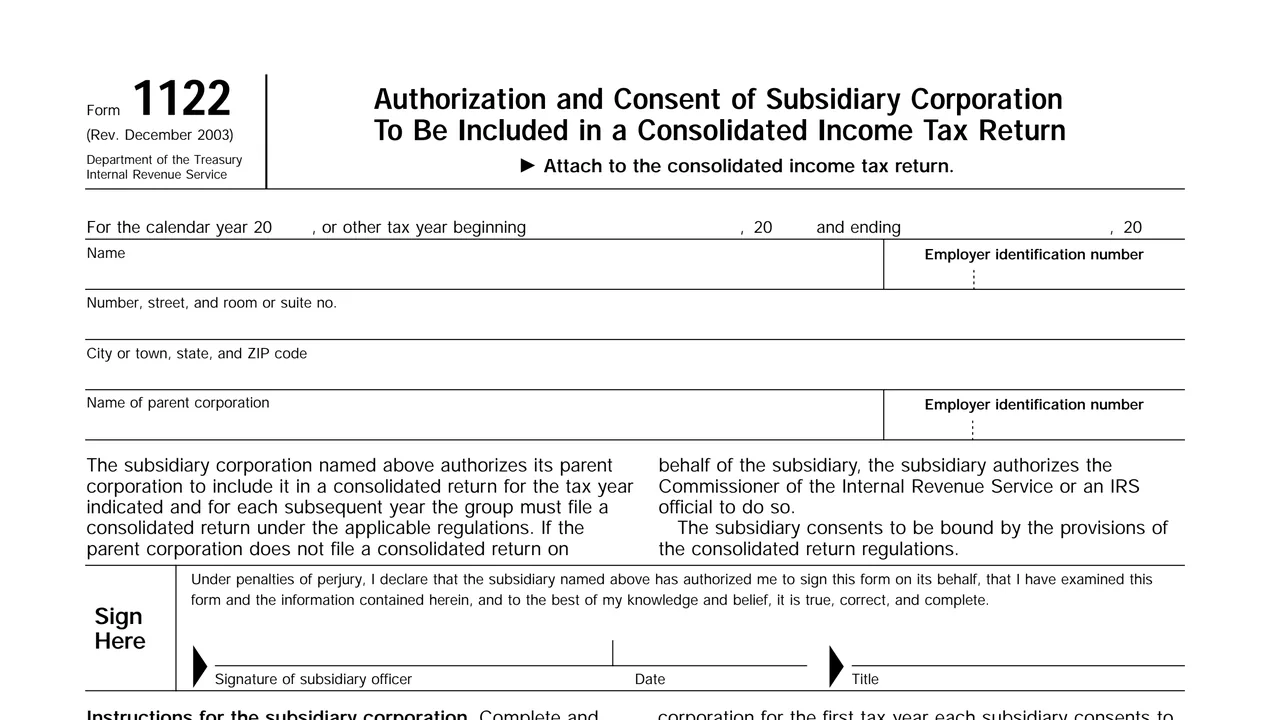
Spaces for the calendar year, or for another tax year with its beginning and ending dates.
The subsidiary's name, employer identification number, street address with room or suite number, and city or town, state and ZIP code.
The name of the parent corporation and its employer identification number.
The printed statement authorizing the parent, or the IRS if the parent does not file a consolidated return on the subsidiary's behalf, and consenting to the consolidated return regulations.
The signature of the subsidiary officer, the date and the officer's title, under a penalties of perjury declaration.
Enter the calendar year, or the beginning and ending dates of the other tax year, for the first year the subsidiary consents.
Enter the subsidiary's name, employer identification number and full address.
Enter the name and employer identification number of the parent corporation.
An officer of the subsidiary signs, dates and enters a title after reviewing the form.
The form says the subsidiary submits the original, signed form to the common parent corporation of the consolidated group.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to the consolidated income tax return. The parent attaches a separate Form 1122 for each subsidiary.
The form says the parent may attach either the signed Form 1122 or an unsigned version containing the same information stated on the signed form.
The form says that if the parent submits an unsigned Form 1122, it retains the original, signed form in its records.
The consent covers the tax year shown and each later year the group files a consolidated return under the applicable regulations.
Two corporations handle the form: the subsidiary signs it, and the common parent corporation of the consolidated group files it with the return.
No tool matches that search.
An officer of the subsidiary corporation, under penalties of perjury, with the date and the officer's title.
No. The form says the subsidiary submits it to the common parent corporation, and the parent attaches it to the consolidated income tax return.
The form is for the first tax year a subsidiary consents to be included. Its consent covers that year and each later year the group files a consolidated return under the regulations.
Yes. The form says an unsigned version with the same information may be attached, and the parent then retains the original, signed form in its records.
The form says the subsidiary authorizes the Commissioner of the Internal Revenue Service or an IRS official to do so on its behalf.